Upgrading your home’s energy system is a big decision. In recent years, volatile energy prices and the rising cost of living have made households rethink how they use their energy, including looking for ways to lower monthly bills, stay protected from future price increases, and reduce their home’s carbon footprint.
Moving to technology like solar panels or battery storage can cost a lot upfront, and while the long-term benefits may look appealing, the starting cost can still feel hard to manage. The new Warm Homes Loan Scheme is designed to help with that – launched in October 2026 as part of the government’s Warm Homes Plan, it makes borrowing for home energy upgrades cheaper through participating lenders.
So, how does the Warm Homes Loan Scheme fit into the wider Warm Homes Plan, how does it differ from a grant, which home energy upgrades does it cover, and what are the rules you need to follow?
What is the Warm Homes Loan Scheme?
The Warm Homes Loan Scheme is aimed at helping property owners spread the upfront cost of home energy upgrades. Instead of paying one large amount at the start, you may be able to finance eligible home energy technology through accessible monthly payments, at a lower interest rate than some standard loans.
This scheme sits under the government’s wider Warm Homes Plan, helping to make UK homes more energy efficient, lower household bills, and reduce reliance on fossil fuels.
You may already see the value in generating some of your own energy, but the upfront cost can still feel out of reach. By working with participating lenders, the government aims to offer a clear and regulated way to help fund these improvements more affordably.
It is important to remember that this is a loan, so the money borrowed needs to be paid back over an agreed period. However, the aim is to make repayments and interest rates more manageable than they might otherwise be for households looking to unlock access to energy savings.
Warm Homes Loan vs. Warm Homes: Local Grant – what’s the difference?
People often mention the two in the same breath, but one is money you borrow and the other is funding you don’t pay back. Here’s how they compare:
| Warm Homes Loan Scheme | Warm Homes: Local Grant | |
|---|---|---|
| What is it? | Government-backed loan with a reduced interest rate. | Fully funded energy-saving upgrades for eligible low-income households, delivered by local councils. |
| Do you pay it back? | Yes, in monthly repayments. | No. |
| Is it open now? | Yes, through participating lenders. | Depends on your council. Some have reached their funding limits and are running waiting lists*. |
| Who’s it for? | Homeowners and private landlords. | Low-income homeowners and private tenants. |
| Any income checks? | No government income limit, but approved lenders run their own checks. | Household income usually £36,000 or less, or certain benefits or postcodes. |
| EPC rating requirement? | No. | Yes, D to G. |
| Where is it available? | Across the UK. | England only. |
| What can it pay for? | Solar panels, battery storage, heat pumps and other low-carbon tech. | Solar panels, insulation, heating upgrades and low-carbon heating. |
| How much can you get? | Varies by technology, e.g. up to £15,000 for solar panels. | Up to £30,000 per home. |
| How do you apply? | Through a participating lender, not the government. | Through GOV.UK or your local council (if accepting applications). |
*Because the Warm Homes: Local Grant is run by local councils, funding is limited and it depends on where you live. MoneySavingExpert says some councils have already run out of funding due to high demand and aren’t taking new applications right now.
The Warm Homes Loan Scheme, on the other hand, is open now across the UK, with no income limit or EPC requirement, and you choose the upgrades and installer that suit your home.
Can you use a Warm Homes Loan with another grant?
Yes, but only with select grants. The Boiler Upgrade Scheme in England and Wales and Home Energy Scotland grants are designed to work with a Warm Homes Loan, even on the same installation. The grant takes money off the total cost, and the loan can then cover what’s left.
For example, if an air source heat pump costs £15,000 to install and you qualify for a £7,500 Boiler Upgrade Scheme grant, your bill drops to £7,500. You could then use a Warm Homes Loan to cover the remaining £7,500 and spread it over monthly payments.
However, the Warm Homes: Local Grant works differently. It’s an alternative for lower-income households rather than a top-up. Apart from the Boiler Upgrade Scheme and Home Energy Scotland grants, you can’t use a Warm Homes Loan and other government funding to pay for the same home improvement.
Who qualifies for the Warm Homes Loan Scheme?
To use the scheme, you will usually need to meet certain rules to make sure the finance is used for the right type of property and that repayments are affordable for your household’s budget.
- Property Ownership: The scheme is aimed at UK homes, and you must own the property you want to upgrade – this includes owner-occupiers, who own and live in their homes. Private landlords can also apply, as improving the energy efficiency of rented homes is part of the wider Warm Homes Plan.
- Financial Eligibility: You will usually need to go through credit and affordability checks, as lenders will need to check that you can manage the repayments alongside your other regular costs. This is not the same as an income-tested grant, but your finances will still be reviewed.
- Property Suitability: Your home also needs to be suitable for the upgrade you want. For example, if you want solar panels, you will need a roof that gets enough daylight and is suitable for installation. For some low-carbon heating systems, lenders or installers may ask to see your EPC rating – this helps show whether your home is insulated well enough to get the best result from the system.
Which energy-saving improvements are covered?
The Warm Homes Loan Scheme is designed to help pay for technologies that can reduce how much energy you buy from the grid. Solar panels and battery storage are two of the most popular upgrades the scheme covers, and they’re exactly what we specialise in at Utilita.
Solar panels (Solar PV)
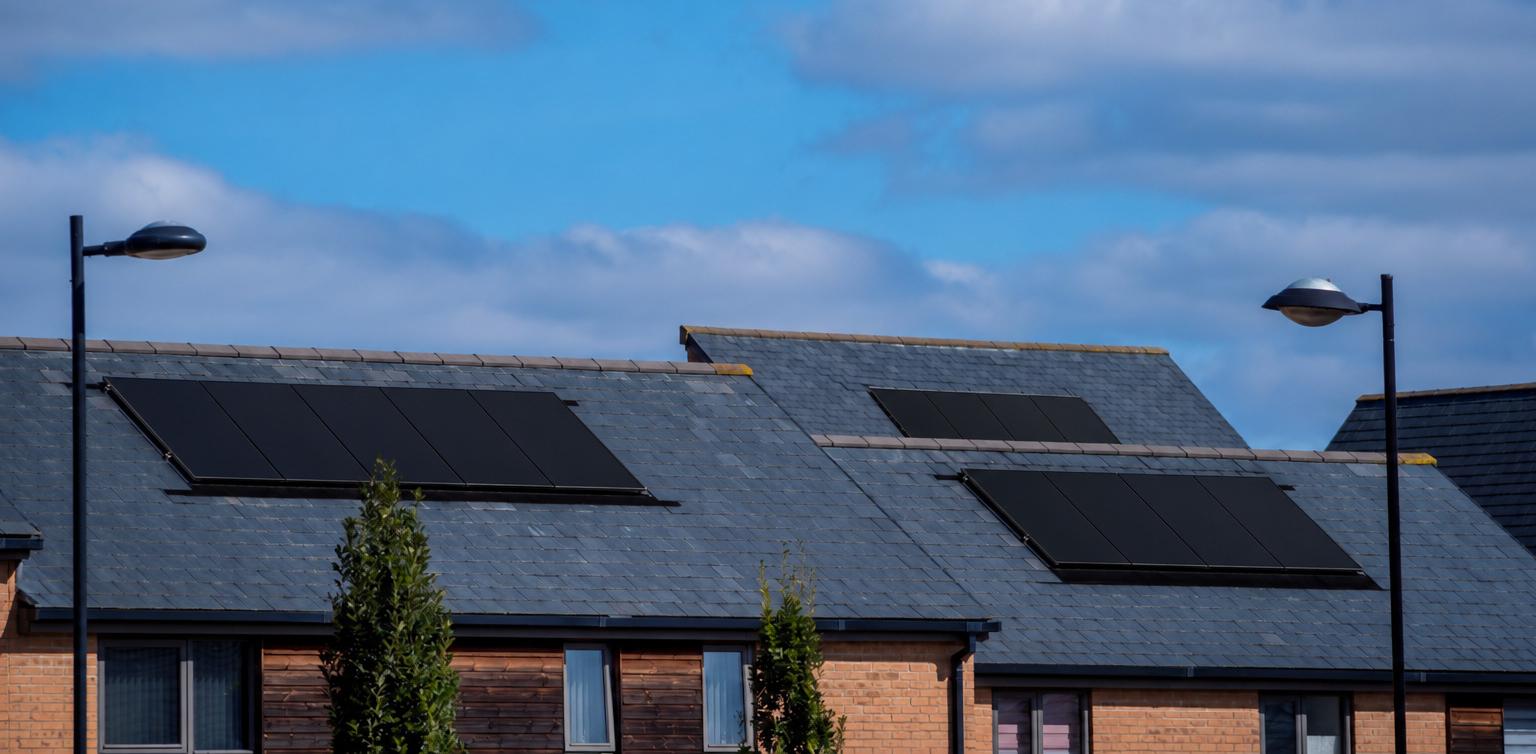
Solar panels turn daylight into electricity for your home, so they still work on cloudy UK days. By generating some of your own power, you may buy less from the grid, which is why many people consider solar when they want more control over their energy use.
Maximum loan: £15,000
Battery storage
A home battery stores extra electricity made by your panels during the day, so you can use it later. This can help you get more value from the electricity your system produces.
Maximum loan: £15,000
Low-carbon heating
Heating is one of the biggest parts of home energy use. While Utilita don’t actively supply or install these, the scheme also covers low-carbon heating systems that replace gas or oil boilers, including:
- Air-to-water heat pumps (up to £20,000): These take heat from the outside air and work with your wet central heating, such as radiators.
- Air-to-air heat pumps (up to £10,000): These take heat from the outside air and blow warm air into your home. They’ll be eligible once MCS certification is available for them.
- Ground source heat pumps (up to £35,000): These work in a similar way, but they take heat from pipes buried in the ground.
- Biomass boilers (up to £20,000): These burn wood pellets, chips or logs to heat your home and hot water.
- Heat network connections (up to £7,500): If your area has a district heating network, the loan can help with the cost of connecting your home.
Other eligible technologies
The scheme also covers micro-renewable systems, such as domestic wind turbines and micro-hydro systems, up to £20,000. These are less common for most homes.
You can see the full list of loan limits on GOV.UK.
Warm Homes Loan Scheme rules: Do you need an approved installer?
Yes, under the scheme rules a Microgeneration Certification Scheme (MCS)-certified installer must fit your home energy upgrades, and you can’t install them yourself. MCS certification shows an installer meets recognised industry standards and uses approved products. It’s also worth checking they’re a member of a consumer protection scheme such as RECC or TrustMark.
At Utilita, all our solar panel and battery installations are carried out by trusted, MCS-certified installers, so when going solar with us, you can be reassured that you’re in safe hands. But don’t just take our word for it, read about what our customers have to say on Trustpilot.
How does the Warm Homes Loan make borrowing cheaper?
The government has worked with participating lenders to cut interest rates by up to 5% compared with standard high-street loans. Each lender sets its own rates, repayment terms and checks, so it’s worth comparing the total cost, loan length and any fees before you choose.
Remember, how much you can borrow depends on the technology you’re looking to install, for example up to £15,000 for solar panels and up to £15,000 for battery storage.
How to apply for a Warm Homes Loan
Taking time to understand your options is often the best way to start, so here’s a clear breakdown of what you could expect when applying for the Warm Homes Loan.
Step 1: Understand your home’s needs
Start with what you want from your system. You may want solar panels to generate electricity, or a battery to store some of that power for later. If you’re not sure where to start, our guides on whether solar panels are worth it and whether solar batteries are worth it can help you decide what suits your home.
Step 2: Get a tailored quote from an accredited installer
Before you apply for finance, get a clear quote. Ask an MCS-certified installer to set out the cost of the system, installation, any extra work, and the warranties included.
Step 3: Apply through a participating lender
Once you have your quote, you can apply with a participating lender. They will usually carry out credit and affordability checks – and may also check that the installer and technology meet the scheme rules.
Step 4: Installation and aftercare
If your loan is approved, your installation can go ahead. Your installer should work carefully, keep disruption low, and explain each stage. Once everything is set up, they should show you how to use any app or monitoring tool. Good aftercare and clear warranties matter just as much as the installation.
Thinking of installing solar for your home?
Utilita are working with one of the ten approved lenders for the Warm Homes Loan Scheme, so watch this space for more details soon.
In the meantime, our Solar Calculator can show you what you could save with a solar and battery package. Just enter a few details about your home and energy use to get your free, personalised quote. Or request a callback and one of our Home Energy Consultants will be in touch within 30 minutes (Monday to Friday, 9am to 5pm) to talk you through your options.